
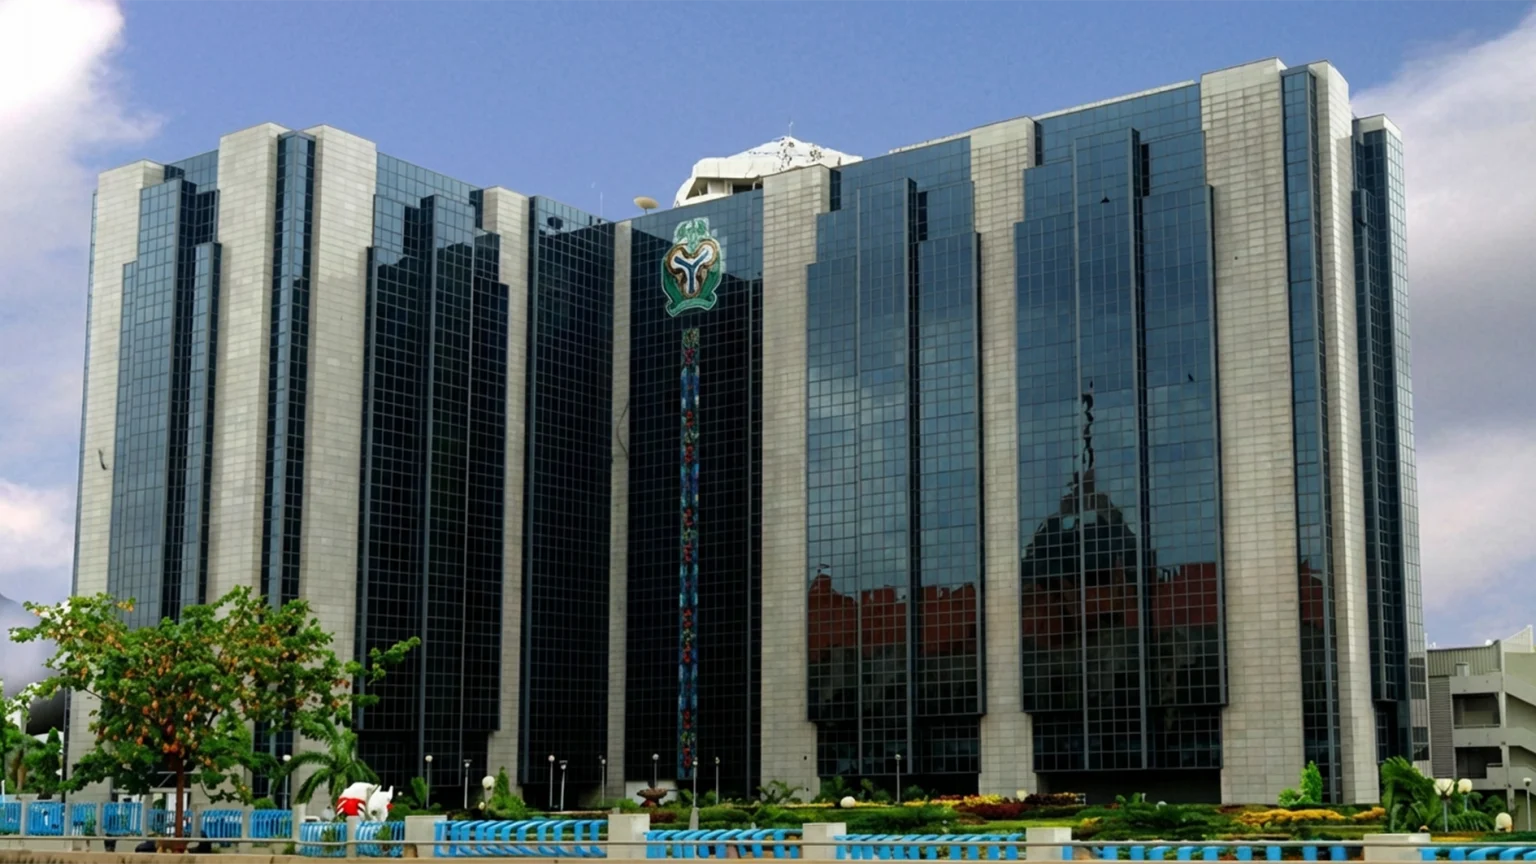
Central Bank of Nigeria headquarters, Abuja.
Credit to Nigeria’s private sector fell by N537.6 billion in September 2026, despite remaining significantly higher than its level a year earlier, raising fresh questions about the flow of financing to businesses and households amid persistent concerns over borrowing costs.
Data from the Central Bank of Nigeria (CBN) showed that credit to the private sector declined to N83.93 trillion in September from N84.47 trillion in August, representing a month-on-month contraction of 0.64 per cent.
However, on a year-on-year basis, private-sector credit increased by approximately N11.40 trillion, or 15.7 per cent, from N72.53 trillion recorded in September 2025.
The latest figures indicated that although credit extended to the private sector has expanded over the past year, the monthly decline points to a reversal of the growth recorded in August.
The development comes amid concerns about the availability and affordability of credit for businesses, particularly manufacturers and
small and medium-sized enterprises, which require working capital to sustain production, manage operating expenses and finance expansion.
A breakdown of the CBN’s money and credit statistics showed that private-sector credit rose from N75.83 trillion in December 2025 to N93.74 trillion in January 2026 and further to N94.61 trillion in February before dropping to N80.73 trillion in April.
Credit subsequently recovered, reaching N83.60 trillion in July and N84.47 trillion in August before declining in September.
The figures, however, do not establish whether the latest contraction resulted from weaker demand for loans, repayments, tighter lending conditions or other factors.
This decline also comes after the CBN’s September decision to reset its benchmark Monetary Policy Rate (MPR) from 26.5 per cent to 23 per cent, a reduction of 350 basis points at the Monetary Policy Committee’s 307th meeting. The adjustment was the largest reduction in the benchmark rate since December 2006.
The apex bank said the adjustment was intended to strengthen monetary policy transmission and restore the MPR’s effectiveness as the principal signal for interest rates in the economy.
However, industry experts have argued that a reduction in the benchmark rate does not automatically translate into cheaper loans or increased lending to businesses, as banks’ lending decisions are also influenced by their funding costs, risk assessments, liquidity positions and borrowers’ creditworthiness.
For businesses, access to affordable financing remains important for inventory purchases, equipment acquisition, payroll and other operating expenses, especially in the current business environment where high borrowing costs continue to constrain investment and production.
The September decline therefore highlighted the need to assess the impact of monetary policy changes not only through benchmark interest rates but also through actual lending conditions and the volume of credit reaching productive sectors.